

U.S. Bank Mobile Banking

- 217.45K Reviews
- 4.7
- Downloads
- 10,000,000+
Our take on U.S. Bank Mobile Banking from Appgk
Managing money from a phone sounds simple until an app makes an everyday task feel slower or less clear than it should. I spent time with U.S. Bank Mobile Banking to see where it fits in real life, from checking a balance before a purchase to keeping an eye on several accounts during a busy week. My overall impression is of a practical banking companion rather than a broad personal-finance planner: it is most useful when your financial life already runs through U.S. Bank and you want routine account access in your pocket.
This is a free finance app developed by U.S. Bank Mobile, with an Everyone age rating. Its long presence on mobile is notable: it was released on October 4, 2011, and the current version is 3.80.70. That history matters because banking apps have to balance familiarity with ongoing maintenance. A redesign can make navigation feel fresher, but it can also force existing customers to relearn actions they perform under pressure. Here, the value is less about novelty and more about having a dependable digital doorway into a U.S. Bank relationship.
How U.S. Bank Mobile Banking fits into daily money management
The app makes the most sense for someone who wants a direct view of their U.S. Bank finances without opening a desktop browser. I found that its strongest role is the quick check: confirming whether a payment has cleared, reviewing recent activity, or making sure an expected deposit has appeared before committing to a purchase. Those small moments add up, especially for people who prefer to resolve money questions immediately rather than postpone them until they are at a computer.
It also suits users who already think of their bank as the central place for everyday money. Instead of switching between a bank website, paper statements, and a separate budgeting tool, the app gives the banking relationship a mobile home. That does not make it a replacement for every financial service, but it reduces friction for the tasks that belong specifically to a bank account.
Best Parts of U.S. Bank Mobile Banking
Things to Keep in Mind About U.S. Bank Mobile Banking
One realistic example is a grocery trip near the end of a pay period. I would open the app before reaching the checkout, check the available balance and recent transactions, and look for any pending charge that might change the amount I can safely spend. That is a more useful habit than relying on memory or a balance from several days earlier. The app is valuable here not because it offers a dramatic financial insight, but because it helps turn a vague guess into a timely decision.
The audience is broad, but the best fit is fairly specific. Existing U.S. Bank customers who want mobile access should find the concept immediately relevant. People who rarely use banking apps may appreciate the convenience once they establish a routine. By contrast, someone searching for a complete budget dashboard across many unrelated financial institutions may be better served by a dedicated money-management service, assuming they are comfortable granting that service access to their accounts.
News and Features Related to U.S. Bank Mobile Banking

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
What the current version says about the product’s direction
Version 3.80.70 presents U.S. Bank Mobile Banking as a mature product rather than a brand-new experiment. I would not judge it by the same standards as a small utility app, because a banking application has to preserve trust and predictable access while still improving over time. The important question is whether changes make common actions easier without hiding essential information behind decorative screens.
For an existing user, the current version is best approached with a short orientation session after updating. I recommend checking where account balances, transaction history, transfers, and support options now sit before you need one of them urgently. That is especially sensible if you use the app while traveling or during a payment deadline. A few minutes spent learning the current layout can prevent the frustrating experience of searching through menus when a transaction needs attention.
Don't want to read the full review?
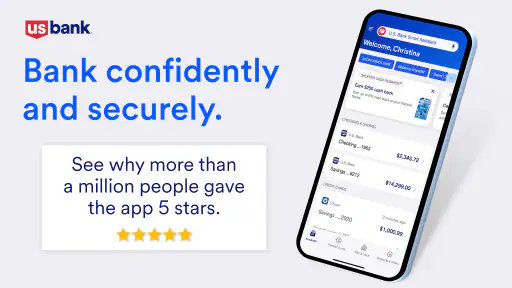
The app’s scale also gives useful context. It has more than 10 million installs, an average rating of 4.7 from around 510 thousand ratings, and roughly 217 thousand written reviews. Those figures suggest that mobile banking is a well-established part of how many customers interact with U.S. Bank, while the rating indicates a generally positive reception. I still would not treat a high average as proof that every workflow will suit every person. Banking needs vary, and a customer who wants detailed spending analysis may judge the app differently from someone who mainly checks balances.
The store summary frames the experience as an easier way to manage money, but I think the more accurate interpretation is narrower and more useful: it helps bring ordinary banking tasks closer to hand. That distinction matters. An app can be excellent at account access without being a financial coach, investment research tool, or replacement for speaking with a bank employee.
Screenshots
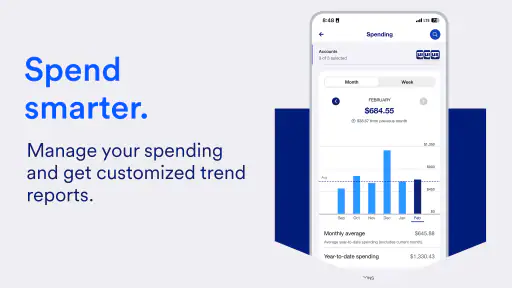
Changes and evolution without losing the basics
Because the app has been available since 2011, its evolution should be understood as a series of adjustments around a familiar banking purpose. The current release is evidence that U.S. Bank continues to maintain the mobile product, but a version number alone does not tell me that every change will be visible or transformative. Some updates in financial apps are deliberately quiet: they may improve compatibility, refine existing screens, or address issues that users only notice when something stops working.
That is why I would separate verified product facts from expectations. The current version is clear, and the app’s long history is clear. What I would not do is assume that a future update will add a particular feature or redesign a particular screen. If you are choosing the app today, judge it by the access and workflows you can use now, not by a hoped-for roadmap.
For long-time customers, continuity is a genuine advantage. You are not starting with an unfamiliar financial service, and the app remains connected to the bank you already use. The trade-off is that mature banking software can feel more cautious than newer finance apps. A specialist budgeting app may present trends, categories, and goals in a more engaging way, while U.S. Bank Mobile Banking keeps its attention closer to the account relationship itself.
I also see an important difference between mobile convenience and mobile completeness. A phone screen is excellent for a quick review, but less comfortable for investigating a complicated history or comparing many transactions. When I need to understand a long sequence of activity, I prefer a larger screen or an exported record if available through the banking relationship. The app’s strength is immediacy; it should not be forced to carry every job that belongs to a full financial review.
How existing customers can get more from it
The most useful habit is to treat the app as a checkpoint, not merely an emergency tool. A quick review after regular income arrives, before a large purchase, and after an important payment can reveal problems earlier than a monthly statement. This is not a substitute for reconciliation, but it makes unusual activity harder to overlook.
A second practical insight is to separate “balance awareness” from “spending permission.” The number visible in an account is not automatically the amount I should spend. Pending activity, scheduled commitments, and purchases that have not fully settled can change the picture. I use the app to review recent movement and upcoming obligations rather than trusting one figure in isolation. That small distinction prevents a common mobile-banking mistake: confusing a momentary balance with a complete view of available money.
A third useful workflow is to use the app before contacting support. I first gather the transaction date, amount, and description, then decide whether the issue is a simple question, a payment timing concern, or something that needs formal attention. Having those details ready makes a conversation more efficient. It also helps me avoid reporting a transaction based only on a vague memory of where I used my card.
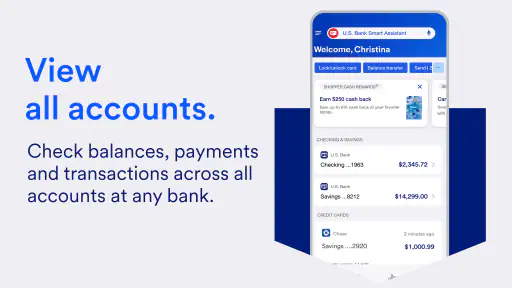
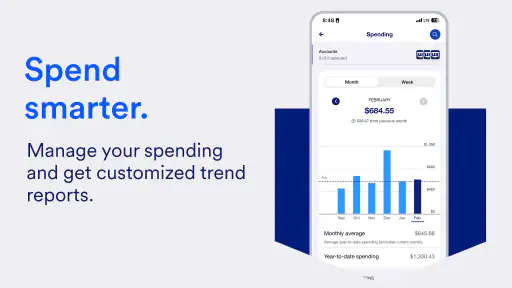
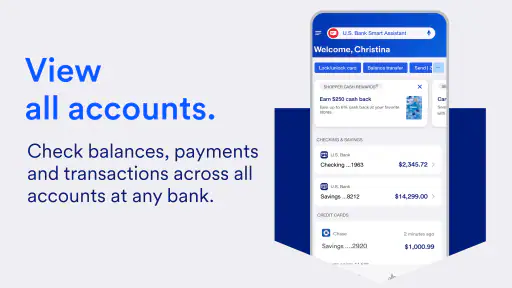
Another trade-off appears when managing more than one account. The app can be convenient for seeing the U.S. Bank side of your finances in one place, but it does not eliminate the need to track accounts held elsewhere. I would keep a separate monthly overview if my income, savings, credit, or household spending is spread across different institutions. This is where an independent budgeting application may be better, although it introduces its own setup and privacy considerations.
For shared household finances, I would also establish a simple communication rule: decide who checks activity and how unusual transactions are discussed. A mobile banking app can make information available quickly, but it cannot resolve disagreements about shared spending. The best result comes from combining timely account review with an agreed household process.
Where it compares well with usual alternatives
Compared with a mobile browser, the dedicated app is the more natural choice for repeated checks. A browser can work in a pinch, but an installed banking app is easier to reach when I want a focused account review rather than a general web session. The convenience is particularly noticeable when the task is brief and I am checking information in the middle of another activity.
Compared with a desktop banking site, the app wins on immediacy but loses some comfort for detailed investigation. A computer remains preferable when I want to examine many entries, organize records, or handle a task that requires sustained attention. I see the two formats as complementary rather than competing: the phone is for timely awareness, while the larger screen is better for careful review.
Compared with a third-party budgeting app, U.S. Bank Mobile Banking has a more direct relationship with the bank account itself. That can make it the sensible first stop for account-specific questions. A budgeting service may offer a broader household picture across institutions, but it may also require extra setup and may present information at a delay or in a more generalized format. I would choose the bank’s app for current account awareness and a separate tool only when I genuinely need cross-institution planning.
Compared with visiting a branch or calling support for every question, the app is clearly more convenient for routine information. It cannot replace human help in every situation, particularly when a matter is sensitive, disputed, or too complicated to resolve through self-service. Still, reducing unnecessary calls is a meaningful benefit for customers who prefer to investigate straightforward issues independently.
Friction points and people who may want another option
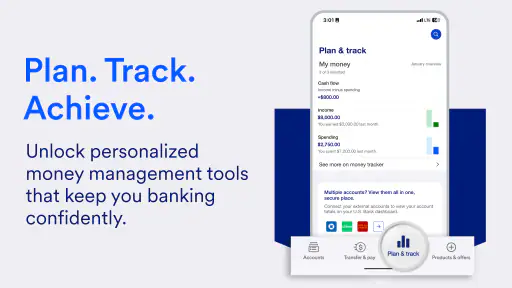
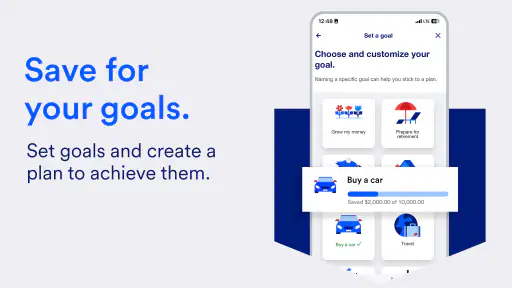
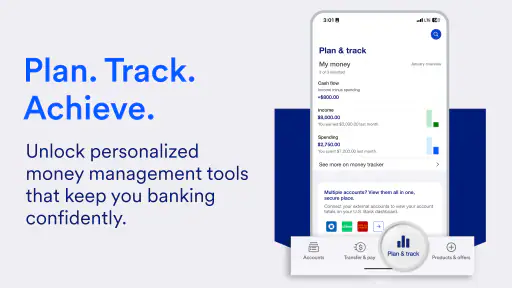
The biggest limitation is scope. This is a banking app, not a complete financial command center. If your main goal is to build a detailed budget, monitor spending categories across several institutions, or plan long-term goals visually, you may find the experience too tied to the U.S. Bank relationship. A dedicated finance tool is likely a better match for that job.
I would also hesitate to recommend it as the only way to manage important finances for someone who dislikes doing sensitive tasks on a phone. A mobile screen can encourage rushed decisions, and notifications or quick checks can create a false sense of control. If you prefer reviewing statements carefully on a computer, the app should be an optional convenience rather than your entire financial routine.
People who do not bank with U.S. Bank should also think carefully about relevance. The app’s value comes from its connection to that institution, so downloading it simply to browse around does not make much sense. The same is true for users who need a neutral tool that combines accounts from many banks. In that case, an independent service may better match the goal, provided its access model is acceptable to you.
There is also a human limitation that no interface can remove: mobile access makes it easy to check money, but not necessarily easy to understand it. If you are dealing with debt, irregular income, or complicated household expenses, seeing transactions is only the first step. You may still need a spreadsheet, a counselor, or a longer planning session. I appreciate the app more when I use it as reliable information for those decisions, not as a promise that the screen will make them for me.
What I would watch as the app continues to evolve
For future updates, I would pay attention to whether routine actions become clearer without adding unnecessary layers. Banking apps should make the path from opening the app to understanding an account feel calm and predictable. I would particularly value improvements that help distinguish completed activity from items still in motion, because that distinction is central to responsible spending decisions.
I would also watch how the experience serves both quick checks and deeper reviews. A strong mobile design can support a fast balance glance while still offering enough context to investigate a transaction. Those goals can conflict: showing too little creates uncertainty, while showing too much makes a small task feel heavy. The best updates will respect both types of user.
Accessibility and clarity deserve equal attention. Financial information should be readable in ordinary conditions, understandable without specialist language, and organized so that a customer can find help when a transaction looks wrong. I do not need visual novelty from a banking app; I need confidence that an important detail has not been buried.
Finally, I would judge future releases by how well they preserve trust for established users. A mature app has customers who have built habits around it. Meaningful improvements are welcome, but abrupt changes can carry a real cost when people need to act quickly. The healthiest evolution is one that improves the experience while keeping familiar financial tasks recognizable.
My recommendation is straightforward: if you already use U.S. Bank and want a free way to keep up with your accounts from an Android or iOS device, U.S. Bank Mobile Banking is a sensible choice. Its mature history, strong user reception, and current version make it feel like an established part of the bank’s service rather than an afterthought. I would use it for timely checks, transaction awareness, and everyday account access.
I would not choose it as my only financial tool if I needed detailed cross-bank budgeting or a broad planning workspace. In that situation, I would pair the bank app with a separate method for organizing the bigger picture. The best reason to install U.S. Bank Mobile Banking is not that it does everything; it is that it puts the bank tasks you actually perform most often within easy reach. For existing customers who value that kind of direct access, U.S. Bank Mobile Banking earns a recommendation, with the sensible reminder to use it as part of a thoughtful money routine rather than as a replacement for one.
U.S. Bank Mobile Banking FAQ
What can I do with the U.S. Bank Mobile Banking app?
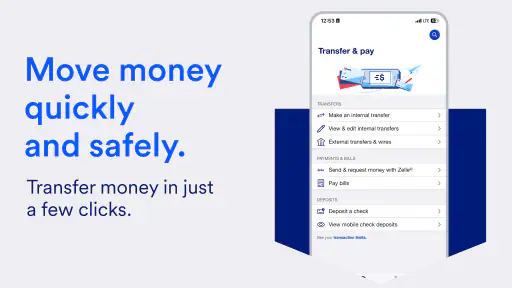
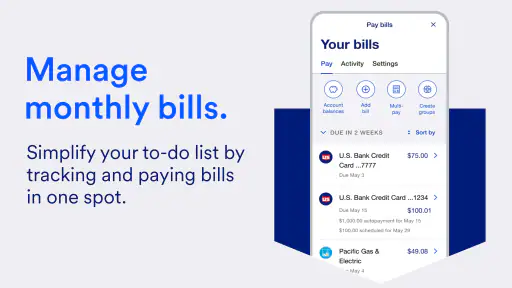
The U.S. Bank Mobile Banking app lets customers manage many everyday banking tasks from an Android or iOS device. After signing in, you can review balances and transactions, transfer money, pay bills, deposit eligible checks, manage cards, locate branches and ATMs, and receive account alerts. Available features may vary depending on your account type, location, device, and current U.S. Bank services.
Is the U.S. Bank Mobile Banking app safe to use?
U.S. Bank Mobile Banking includes security features designed to help protect your financial information, such as encrypted connections, secure sign-in options, device authentication, and alerts for account activity. However, no banking app eliminates every risk. Use the official app-store listing, keep your operating system updated, avoid public Wi-Fi for sensitive tasks, and never share passwords, verification codes, or security answers with anyone.
Can I deposit checks using the U.S. Bank Mobile Banking app?
In many cases, eligible U.S. Bank customers can deposit checks by photographing the front and back of the endorsed check through the mobile deposit feature. The app normally provides instructions for image quality, endorsement, and confirmation. Deposit limits, availability of funds, eligibility requirements, and processing times can differ by account and customer, so review the terms shown in the app before submitting a deposit.
Does the app charge fees for mobile banking or transfers?
Downloading and using the U.S. Bank Mobile Banking app may not carry a separate app-access fee, but normal account terms can still apply. Depending on the service, you could encounter fees related to overdrafts, certain transfers, expedited payments, non-U.S. Bank ATMs, wire transactions, or other account activity. Check the fee schedule for your specific account and carefully review any confirmation screen before completing a transaction.
What should I do if I cannot sign in or notice suspicious activity?
If you cannot access your account, confirm that you are using the latest official app, check your internet connection, and use the available password or username recovery options rather than repeatedly guessing credentials. For a locked account, failed verification, lost device, or suspicious transaction, contact U.S. Bank through a verified official channel. Do not rely on phone numbers or links received unexpectedly by text, email, or social media.











